
October 22, 2026
Grain Overview
Grain futures stayed mostly mixed overnight, with wheat futures remaining the weakest link. Black Sea developments continue to pressure wheat prices as traders anticipate a possible agreement to reopen grain shipping. Putin has agreed to resume U.S.-mediated peace talks, possibly around November 10, but has not agreed to reopen shipping routes. Russia has reportedly rejected a proposal involving Turkey, India, and Egypt to protect grain vessels, leaving Ukrainian exports at just 38% of normal levels.
That means another 3 weeks of restricted grain movement, at least. The current break in wheat prices seems overly optimistic for an agreement that remains 50-50 at best. Putin knows prolonging fighting through the winter strengthens his hand in negotiations to retain Donbas and Crimea, as Zelensky wants some of that back.
Corn and soybeans yesterday revealed support, with corn reversing early-session losses and putting in a key reversal into the close. Overnight gains from that were minor, but corn did eke out an opportunity to trade above Wednesday’s high before retreating modestly. Export sales data out this morning at 7:30 a.m. should be strong for soybeans, with corn showing an improvement over the prior week’s numbers.
Northern Iowa and southern Minnesota are reporting reasonable yields, if not better than expected, while Central Iowa and south reports yields up to 15% below last year, along with increased fungus issues from excessive summer rain. Some areas of the ECB are reporting yields 20% below a year ago. These variable yields are keeping corn sales minimal as farmers sell soybeans to make more room for corn storage, supporting basis. With the lowest August-September crop ratings in 5 years, it’s hard to justify a national yield 5 BPA above the 10-year average of 176 BPA. The truth may be somewhere south of 180.
December crude oil overnight again challenged $100 and is presently near 99.00, up almost $2.00 on the session, as the United States is removing US citizens from the Persian Gulf because attacks on US facilities ahead of the midterm elections are a possibility. This has caused energy values to again spike, and this is drawing in managed money. Commodities are becoming oversold, which is helping alleviate price pressure. A good sign for the market yesterday was a flash sale of soybeans to Spain, showing China is not the only point of interest we have. This purchase shows US soybeans are competitive in the global market.
China is up to 16.6 MMTs of beans, with a total obligation of 25 MMTs. Chinese purchasing since last Wednesday has been a daily event, especially with some totals near or over 500,000 MTs. In Brazil, the central and northern regions are turning dry, while the southern areas continue to see rain. This is typical of an El Niño event. What matters is watching the north to see if November rainfall stays reduced as summer heat arrives. Basis remains strong for soybeans, and crush margins are holding near $2.50/bu.
We have another harvest-pressure weekend coming, but by next week, beans should be beyond 80% harvested, while corn will need another 2 weeks to reach that level. Iowa harvest is moving along more slowly. This means hedge pressure will be rearing its ugly head again through this Friday. November 1 typically brings the potential for price relief and new price optimism. November 10 is the next crop production/WASDE report.
Cattle Overview
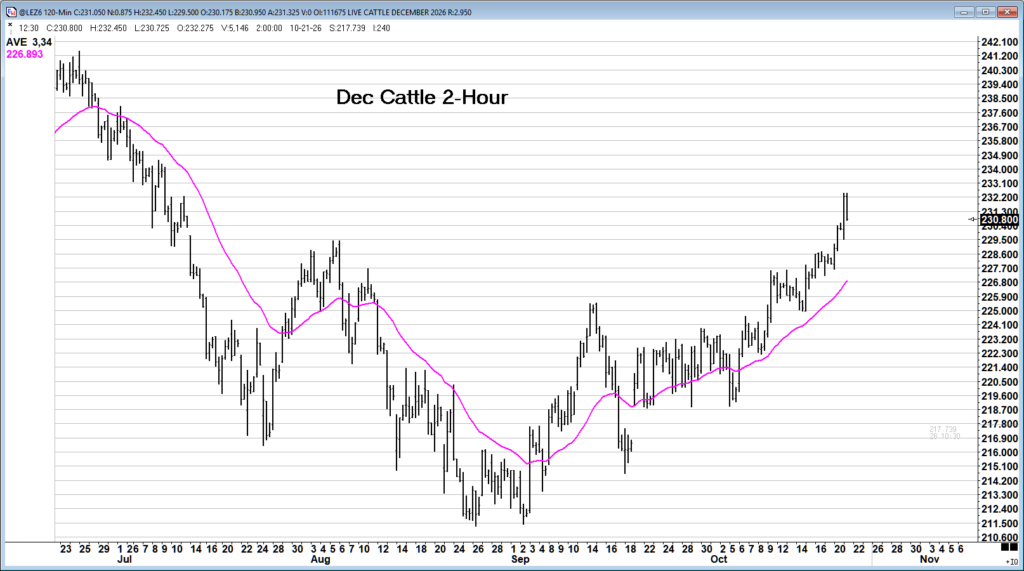
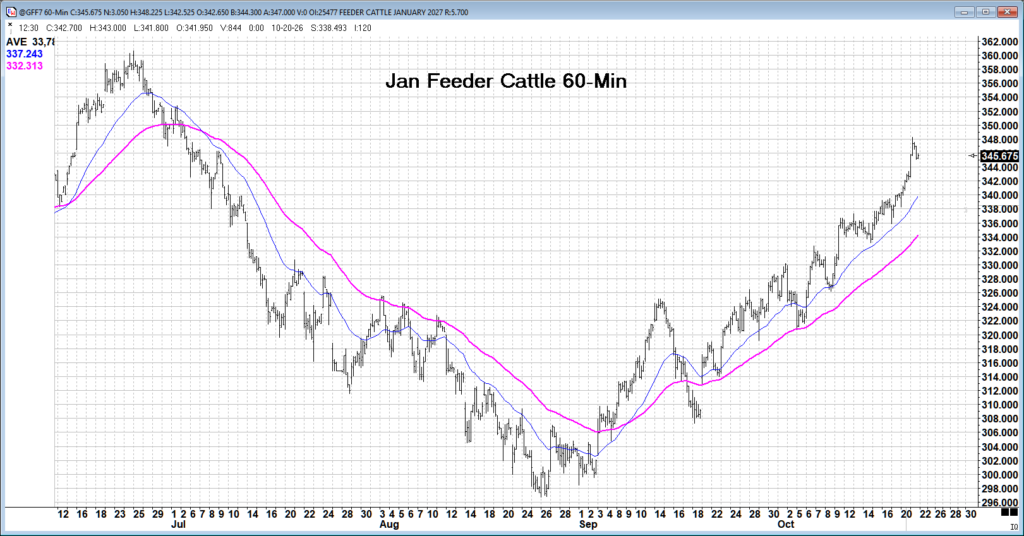
Cattle futures did another morning wiggle yesterday and again exploded higher on the session, pushing strong gains into midsession. The key observation is that the trade did retreat into the close, with December cattle stalling at its daily high just shy of its 50% retracement on the continuation charts from the summer May high near 233, and January feeders stalling at their 78% retracement above 347 before settling with gains at the midpoint of the session. There is nothing wrong with the closes, other than the market did find what are likely extreme values for now ahead of an expected bullish COF report Friday afternoon.
Asking prices in the South have already surfaced at 232, but none have been established in the North. October cattle trade certainly implies 230 or better is possible, but we likely won’t see the trade until after this COF report. Boxed beef yesterday did soften, with choice down $0.71 at $372.59, while select gave up its prior-day gains and was lower by $6.20 at $355.34. Movement continues to be reasonable at 91 loads, with 63 choice, 10 select, almost 13 loads of ground beef, and the rest trim.
Yesterday’s feeder index showed a modest gain of $0.62 at $342.78, but it was the daily number that was encouraging for the feeders, as it was at $349.72 on 1,624 head. October feeders yesterday almost kissed that daily number before a light retreat into the close. Cash settlement into next week will be interesting.
Cattle futures have now entered an extended price area that warrants caution. Live cattle futures will eventually advance higher into the end of the year, but in the shorter term, they are entering a window where these gains can get checked. The optimism that develops in October on the futures typically gives way to weakness in November. December live cattle near 233 or anything higher becomes a short-term sellable premium. The same thing goes for January feeder cattle. Attempts to challenge 250 are also likely extended for now.
Support on December cattle, because of recent gains, is now a bit under the market at 227.00-227.50. January feeder cattle are so elevated currently that they do not have initial support until 339.50-340, with major support at 334.
Any Questions and to inquire about Livestock Risk Protection Insurance Call: 701-222-0221
Past performance is not indicative of future results. The information contained in this report is intended for informational purposes only and is the opinion of the writer and may change at any time. This information was compiled from sources believed to be reliable to Heartland Investor Capital Management, Inc. but accuracy cannot be and is not guaranteed. There is no warranty, expressed or implied, in regards to this information for any particular purpose. There is SIGNIFICANT RISK of LOSS involved in trading futures and / or options on futures and may not be suitable for all investors. Investors should consider these RISKS and evaluate their suitability based on their financial conditions. No one should ever consider trading futures or options on futures with anything other than RISK CAPITAL. NO LIABILITY on the part of the author exists for any trading loss you may incur in the use of this information. The information contained in this newsletter is privileged, confidential and protected from disclosure. Any further disclosure or use, distribution, dissemination or copying of this message or any attachment is strictly prohibited. Provided by Heartland Investor Capital Management, Inc. a registered CTA with the NFA, of which Eugene Graner is principal. This entity is a separate legal entity from the Introducing Broker Heartland Investor Services.