
October 19, 2026
Grain Overview
Grain futures opened soft Sunday evening and quickly turned mixed, with wheat trying to lead. A sizable reduction in the Australian crop outlook helped support wheat. Meanwhile, talk of peace continues as the war in the Black Sea region goes on. Somehow, the talk of Pres. Trump, Putin, and Xi in a summit could bring about a settlement. Talk and tweets are all that have occurred since early September, and wheat from the Ukraine/Russian region remains near 50%.
Corn and soybeans traded mixed overnight as the US harvest should make excellent progress through October 24, with no widespread frost threat expected until November. That should give farmers who have fallen behind a chance to catch up. Reports of overly dry corn are expanding. Basis values remain strong across the board, though, as farmers are disengaged from marketing and focused on fieldwork.
In Brazil, weekend rains brought much-needed moisture to Mato Grosso, Bahia, and São Paulo. They’ll need it, as hotter, drier weather is forecast to return across the northern two-thirds of Brazil late this month. Soybean planting remains at or ahead of normal in most areas, except São Paulo. The main area of interest is Central and Northern Brazil, where drought tends to develop in El Niño events.
Ethanol margins remain strong and are at $0.50/gallon. The fund long position has now been reduced to 231,000 contracts. Meanwhile, soybean crush margins are at $2.70/Bu. Meal demand continues to build, and the fund’s long bean position is also down to 238,000 contracts. Index funds are short 33,000 contracts of Chicago but long 17,000 Kansas City.
Overnight action could have been much softer, but day-session selling vigilantes have more power when the cash grain trade joins them in selling mode at the 8:30 a.m. day session. November soybeans fell to a low of 12.53 on Friday, with major breakout support on the continuation chart at 1240-1245. December corn is retesting the crop-report low, looking for further export news similar to Japan’s flash sale of over 100,000 MTs on Friday. Chicago wheat continues to flounder in the 660-price range, searching for a new buying catalyst.
How the row crop markets perform this week, driven by harvest pressure, will be key, as farmers will likely have harvest at 80% for beans and 60% for corn. By mid-next week, harvest pressure will be in the rearview mirror.
Cattle Overview
Another spectacular week for cattle trade last week as the South pushed back at 226 and settled on a 228 cash price to get the negotiated trade in full swing. What’s interesting is that September data on beef imports showed we only picked up an extra 30,000 MTs of beef trimmings, and with the relaxed tariffs set to end on November 30, imports will be nowhere near what was advertised. Cattle trade has risen $10.00 since the August cash trade low of 218 was printed.
This Friday’s Cattle on Feed report is set to reveal again another historically low placement rate into feedlots. This is why feedlots continue to compete more strongly for calves, even though Mexican imports are occurring and are expected to increase further as Columbus, New Mexico, opens within another week. As I said last month, there is talk that the lower placement rate could also signal higher heifer retention building for herd growth that won’t be felt until next fall. This could be the 2027 surprise when the USDA puts out the herd size again on January 31.
By the numbers, December cattle closed above 228, with October right on its tail. This opens up the door to 231-233. Intraday support for December cattle is now at 226.75-227.25. Major support is 225.
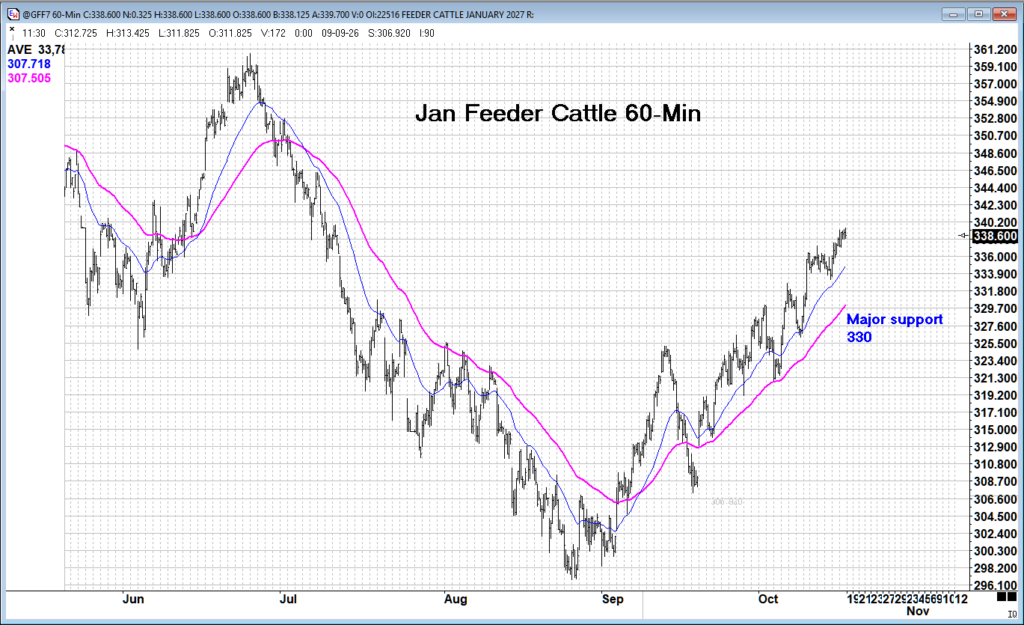
November feeder cattle closed near the high of their trading range on Friday, near 342, after stalling all week. 344 is a measured target they still could reach. January feeders will take over the continuation chart this week, so they also have an upside target of 342 in sight. January feeder cattle now have support at 335-335.50. If it gets rocky, major trend-following support is at 330.
Any Questions and to inquire about Livestock Risk Protection Insurance Call: 701-222-0221
Past performance is not indicative of future results. The information contained in this report is intended for informational purposes only and is the opinion of the writer and may change at any time. This information was compiled from sources believed to be reliable to Heartland Investor Capital Management, Inc. but accuracy cannot be and is not guaranteed. There is no warranty, expressed or implied, in regards to this information for any particular purpose. There is SIGNIFICANT RISK of LOSS involved in trading futures and / or options on futures and may not be suitable for all investors. Investors should consider these RISKS and evaluate their suitability based on their financial conditions. No one should ever consider trading futures or options on futures with anything other than RISK CAPITAL. NO LIABILITY on the part of the author exists for any trading loss you may incur in the use of this information. The information contained in this newsletter is privileged, confidential and protected from disclosure. Any further disclosure or use, distribution, dissemination or copying of this message or any attachment is strictly prohibited. Provided by Heartland Investor Capital Management, Inc. a registered CTA with the NFA, of which Eugene Graner is principal. This entity is a separate legal entity from the Introducing Broker Heartland Investor Services.